 Financial coaching
 Savour your spending
When I started working as a financial coach six years ago, I already had more than 20 years of experience in financial services. My career spanned across banking, wealth management and financial planning. I knew plenty about savings, pensions, investments, insurances, mortgages and other debts. But what I’ve learned over the last six years is that helping people make better financial decisions often has surprisingly little to do with financial products. It’s much more to do with understanding people.
As a financial coach, I help people understand their relationship with money and make more confident decisions about their future. That means combining the practicalities of financial planning with the emotions and behaviours around money.
Financial coaching isn’t a cheap substitute for regulated financial advice, nor is it simply about exploring your feelings towards money. It’s a more holistic way of working that goes beyond technical knowledge of money by building self-knowledge.
Sometimes, it can lead to regulated financial advice with clients becoming more equipped to engage confidently with advisers. Other times, clients come away with all the knowledge and skills they need to manage their own finances.
With that in mind, here are six lessons I’ve learned from working with clients over the last six years.
1. Nobody wants to be rich
It feels flippant to say “nobody wants to be rich”. But actually, when my conversations with clients get down to a deeper level, it tends to be true.
I can’t recall a single client who wants to accumulate loads of money for the sake of it. There just doesn’t seem to be any real desire to show off or indulge in lots of material purchases. Sure, people want to build wealth to feel secure for the long-term, but it tends to be in a measured way.
People will say “we’re not looking for a lavish lifestyle, we just want to be comfortable”.
Or “we’re not looking to travel first-class everywhere, but we also don’t want to be backpacking round hostels in our 70s”.
Or “we’re not materialistic and experiences are more important to us than things.”
So if you take “rich” as meaning visibly well-off with the ability to buy whatever you want, that doesn’t really come through as an aspiration from most people. Certainly not with the clients I work with, who are mostly in their 40s and 50s.
In fact, even when I visit the local high school, helping 16 and 17 year olds to learn about money, the word “rich” doesn’t seem to resonate. I usually ask the question “raise your hands if you’d like to be rich when you’re older” and surprisingly few hands go up.
On the other hand, people do want freedom and a sense of independence. As people enter the latter half of working life, it’s often time and health that become the bigger priorities. Strategic financial planning can underpin this, by helping people understand how they can regain more time. Common questions include, “when can I stop working for money?”. Or “can I move to a less stressful job, earn less money and still be ok?”. Or “can I afford to start my own business?”.
It makes me wonder how the National Lottery remains popular, as that’s all based upon the dream of winning a fortune. Anyone I’ve worked with who is serious about planning for the future tends to avoid lotteries.
2. Not everyone wants advice
This is a lesson that carries a degree of complexity, as it depends what’s meant by “advice”. Some people have specifically sought out a financial coach because they’ve realised that regulated financial advice is not for them. But some want to work with a coach for other reasons.
For example, many clients have realised it’s not regulated advice that they need. Their priority might be more on day-to-day budgeting and money management, help getting started with savings or working out the best way to repay debts.
Other people find themselves in a position where they’re asset rich but cash poor, with most of their wealth tied up in property. They’ve found it difficult to get financial advice, because that tends to focus more on the management of investments and pensions.
And some people already have self-awareness that their relationship with money is not where they’d like it to be. They’re seeking a more therapeutic way of working, where they can explore more about their emotions and behaviours around money.
Quite a number of clients have approached me on the back of frustrating conversations with multiple financial advisers. For whatever reason, it just didn’t feel like a good fit, or occasionally, they felt “sold to”.
Yet research suggests that people who do actually work with an adviser are happy with the experience. According to the lang cat’s 2025 Advice Gap Report, 91% of people who had paid for financial advice in the previous two years found it helpful. But still, only 9% of UK consumers had paid for advice during that period.
So while financial advice clearly works well for many people, it isn’t necessarily what everyone needs or wants.
But the real lesson, for me, was that some people just don’t like the concept of “advice” at all. There can sometimes be a deep sense of independence and control that makes it difficult to act upon the advice of others. These are people who much prefer to be empowered to make and implement their own decisions.
Clients who react against the concept of advice tend to be willing to learn deeply, explore options for themselves and perhaps have a “sounding board” to bounce ideas off.
This may be the minority of clients, but fundamentally, these are people who absolutely want to arrive at their own solutions. Sometimes this comes down to a general distrust of advisers and other professionals, but it can also be down to a strong desire to feel in control.
Coaching creates an environment where clients remain the expert in their own lives. It works on the assumption that they are resourceful and can work through problems on a collaborative basis, but retain full control of the decision-making.
In some ways, this shouldn’t really be a “lesson” for me at all, because personally, I’m not a great receiver of advice. Looking back at a total of 18 bosses during my career, I flourished when line managers took on more of a coaching role. I didn’t do so well with micro-management and being told what to do!
3. People rarely do what they say they’ll do
This is in no way a criticism, but a general observation of how full our lives have become. When I first started as a financial coach, I naively thought that I’d help clients to develop action points during a coaching session, then they’d go off and complete them.
I’m not sure why I thought that, because I’m just as bad when it comes to taking action. Especially with things that don’t really interest me or feel difficult. In fact, if procrastination were an Olympic sport, I’d be up there on the medal podium.
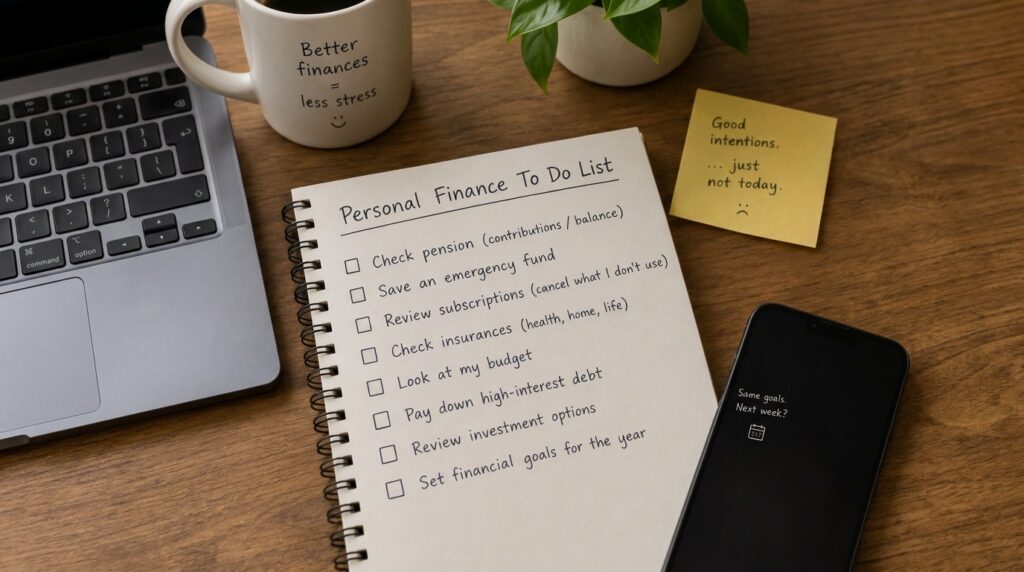
But what’s become evident over the years, is that personal finance has created the illusion of being hugely complex. There is so much information out there. Huge amounts of contradictory ‘advice’ on the internet and social media, continually changing rules as government after government tinkers around with tax rules, pensions and ISA allowances.
It can all lead to overwhelm and, in many cases, it’s easier to take no action at all. That’s the default position for a lot of people.
But even when it’s broken down into manageable steps and micro-actions, stuff still gets in the way. Work, families, health and life keeps throwing stuff that zaps time and energy.
I’ve learned how important it is not to be frustrated when progress isn’t fully achieved by clients. It’s an opportunity to explore what happened and to try out a different approach. There can sometimes be a bit of ‘trial and error’ when it comes to working on finances, and that’s ok.
One of the best things about this work, is when things ‘click into place’ for clients and they make a breakthrough. It might be overcoming a fear of looking at their numbers, or realising that they’re better off than they thought.
When clients reach a place of financial clarity and feel able to think more clearly about the future, the exercise of planning can become a real joy. After a number of coaching and planning sessions, one client said:
“Using a powerful tool called Voyant, we mapped out where I am now, when I’d like to retire, and the path to get there, including how much I should be saving so I’m neither living too lavishly nor too frugally. This led to some huge potential opportunities, including the possibility of one day moving to a four-day working week and, hopefully, even retiring earlier than expected.”
Reaching this degree of clarity required a shift away from procrastination and “paralysis by analysis”. There comes a point where education must turn into action.
Sometimes, a little nudge here and there and a bit of accountability can work wonders.
4. Everyone has money habits that don’t serve them well
With the benefit of hindsight, this one seems obvious. If we accept that most people develop bad habits around eating, exercising, driving and so on, why should money be any different?
Something that makes this lesson a bit trickier is that, generally, we tend not to talk about money with friends and family. It’s not really the “done thing”. So if we’re not talking about it, how can we know that we have bad habits?
I think this has become even more challenging in recent years, as we’ve switched over to a more or less cashless society with easy access to credit.
A couple of decades ago, most transactions were done by cash. You either had physical cash to buy stuff, or you didn’t. It was painfully obvious when you were skint.
Now, the default position for most people is just to tap a bank card, phone or smart watch when making payments. Online purchases are just one click away, with card details stored securely online. That removes a lot of consciousness when spending money and most individuals and couples simply don’t track their spending.
That’s not necessarily a bad thing, but it can be if it leads to overspending and deepening debt.
The opposite is also true. Perhaps having experienced years of scarcity, a lot of people under-spend too. They’ve developed a habit from a place of safety, but now, they’re holding back on life when they could be enjoying much more.
Often, I see habits which are based upon avoidance of money altogether. Many people acknowledge that they “bury their head in the sand” when it comes to money. This can be for a whole variety of reasons, including overwhelm, boredom, confusion, guilt, shame, fear.
It can be tricky to change habits of a lifetime, but once achieved, it can be one of the most transformational shifts that people make.
5. Almost nobody knows where their money goes
It’s a sweeping statement to say that nobody knows where their money goes, but to a certain extent, it’s true. I’m sure there are people who track their spending fastidiously, but I guess they’re less likely to be looking for a financial coach.
And to be honest, it’s not necessarily a problem for people. I’ve worked with people who describe themselves as “quite frugal” but they don’t track everything. It’s just how they are with money and they’re perfectly able to save up and avoid getting into debt.
Some people earn a very high income and don’t feel the need to track spending. They have more than enough coming and just don’t have the time or inclination to think about it.
Financial worries show up in different ways. When lack of spending clarity leads to a monthly deficit building up on credit cards, it eventually gets maxed out.
Or people begin to wonder why they’re not managing to save, despite earning a good income. Over time, agitation sets in as dreams of financial independence feel further and further out of reach.
I’ve heard numerous stories where people have tried budgeting apps, but can’t seem to make it work. Or they’ve started to track things on a spreadsheet or paper, but after a few weeks, it grinds to a halt. This is the practical side of money that feels elusive to many people. In my experience “one size fits all” is most definitely not the case here. It’s important to develop a system that actually works in practice.
One consistency I’ve found, though, is that virtually everyone who completes a detailed breakdown of spending over a few months is surprised and often shocked. Grocery spending is often higher than estimated, and it’s so easy to forget the occasional expenses, like gifts, holiday spending, car and house repairs.
Feeling in control of spending is a fundamental building block towards financial success. I talk about “Savour Your Spending” which is really about developing clarity and gratitude for money that goes out.
The trick is to work out the level of detail that suits you. I’ve learned that money management is a very personal thing and there’s no “best way” to do it. Apps work for some people, but not others. Detailed tracking by category is “fun” for some, but an administrative nightmare for others.
All of this becomes particularly relevant when creating a long-term financial plan for the future. By its very nature, financial planning is inexact and based upon many assumptions. But to build a financial plan based upon guess-work around spending is asking for trouble. We can’t control inflation, interest rates or stockmarkets, but we can control our spending, even if it’s not always easy.
For couples, it’s particularly important to find a system that works for both partners. It’s unlikely that two people will both agree 100% on the same system of money management, so compromise is usually necessary.
6. Forget rules of thumb – you’re not average
I don’t mean this in a literal sense because I do occasionally begin money conversations with a rule of thumb. The trouble is, none of them apply exactly to anyone’s particular situation.
In personal finance, there seem to be loads of them. The “4% Rule” for drawing down an income from investments. The “50/30/20 Rule” for budgeting. The “6 month rule” for emergency savings and so on.
I find these can be good starting points for discussion, but personal finance is nuanced. There really is no “quick fix” that works for everyone and it’s well worth the effort of thinking through your circumstances properly.
What I’ve learned is that, by nature, people tend to want an easy answer. “How much do I need to retire?” is a question where many people hope there’s a standard answer. But there really isn’t one. That’s not to say it’s rocket science and horrendously complex. It just takes a bit of time to explore with a mixture of logic and creativity.
The financial press is full of sensationalism, generalisation and companies trying to sell the “best” solution. When I first started coaching, I even wondered if I could create a scalable ‘system’ that would work for everyone. But no. Genuinely, and I cannot emphasise this enough, everyone’s financial story is absolutely unique and so is their financial plan for the future.
Conclusion
Working as a financial coach and planner is endlessly fascinating. It’s a privileged position and the six lessons above have taken time, patience and compassion to fully digest.
The learning journey has been different, and challenging at times. Way different to the 10 years of study to become a Chartered Financial Planner and Fellow of the Personal Finance Society. But it’s the blend of technical knowledge and the navigation of the behavioural side of money that has led me to create a different kind of support. One that’s entirely separate from product sales or managing other peoples’ money.
It’s a way of working that keeps the client in the driving seat, with support for as long as required – but no longer.
As one client put it recently: “I can honestly say the peace of mind I now have, with my finances and retirement plan in place, is nothing short of life-changing.”
Good financial coaching and planning begins with people, not products.
You can read more reflections from clients on my VouchedFor page.

 Production